

PC DRAM contract prices are expected to rise by 13–18% in the fourth quarter of 2026, even as weakening laptop sales and growing inventories force PC manufacturers to reconsider their memory purchasing plans for 2027. Market research firm TrendForce also forecasts client SSD contract price increases of less than 5% during the same period, reflecting mounting resistance to higher component costs.
In research published on November 11, TrendForce reported that several PC original equipment manufacturers (OEMs) are reducing memory procurement as higher retail prices weaken consumer demand. Some manufacturers have already begun renegotiating their 2027 memory requirements, while others are scaling back SSD purchases through the first quarter of next year.
The findings highlight a growing contradiction in the PC hardware market: memory suppliers continue to face capacity constraints driven by AI infrastructure demand, but PC manufacturers are increasingly struggling to sell systems at prices that reflect rising component costs.
Global notebook shipments declined 15.8% quarter-over-quarter in Q3 2026, according to TrendForce. The research firm expects another potential single-digit percentage decline in the fourth quarter.
Earlier in 2026, PC manufacturers accelerated component purchases and production schedules to secure memory before further price increases. However, higher retail prices have subsequently weakened sales across Asia and Europe, while finished-PC inventories have accumulated among manufacturers and North American distributors.
The combination of weaker demand and rising inventories is prompting manufacturers to reconsider their 2027 product strategies.
TrendForce indicates that some PC brands are considering increasing the proportion of private-label models in their product lineups while adopting lower-specification memory components and CPUs with fewer cores. These changes could help manufacturers control production costs, although the report does not identify specific upcoming laptop models or confirm which brands will implement the proposed configurations.
The potential specification reductions come as 64GB RAM configurations have already lost share in CPU-Z statistics, highlighting broader changes in consumer PC memory configurations amid elevated prices.
Despite weaker PC demand, DRAM prices are still expected to increase.
TrendForce forecasts a 13–18% quarter-over-quarter rise in PC DRAM contract prices during Q4 2026, although the pace of increases is expected to slow compared with the preceding quarter.
Some PC manufacturers previously ordered more DRAM than they immediately needed in anticipation of further price increases. As finished-PC shipments declined, these purchases contributed to growing memory inventories. TrendForce expects the amount of DRAM held by OEMs, measured in weeks of inventory, to increase further during the fourth quarter.
At the same time, memory suppliers are considering reducing PC DRAM supply in 2027 as demand from AI applications continues to influence production decisions.
This reflects the wider pressure on global memory supply from AI infrastructure demand, which has complicated component procurement for consumer electronics manufacturers.
TrendForce suggests that suppliers have some flexibility to moderate price increases while maintaining relationships with major PC customers. However, the projected 13–18% increase indicates that weaker demand has not yet translated into falling PC DRAM contract prices.
The client SSD market is experiencing a similar slowdown, although expected price increases are considerably smaller.
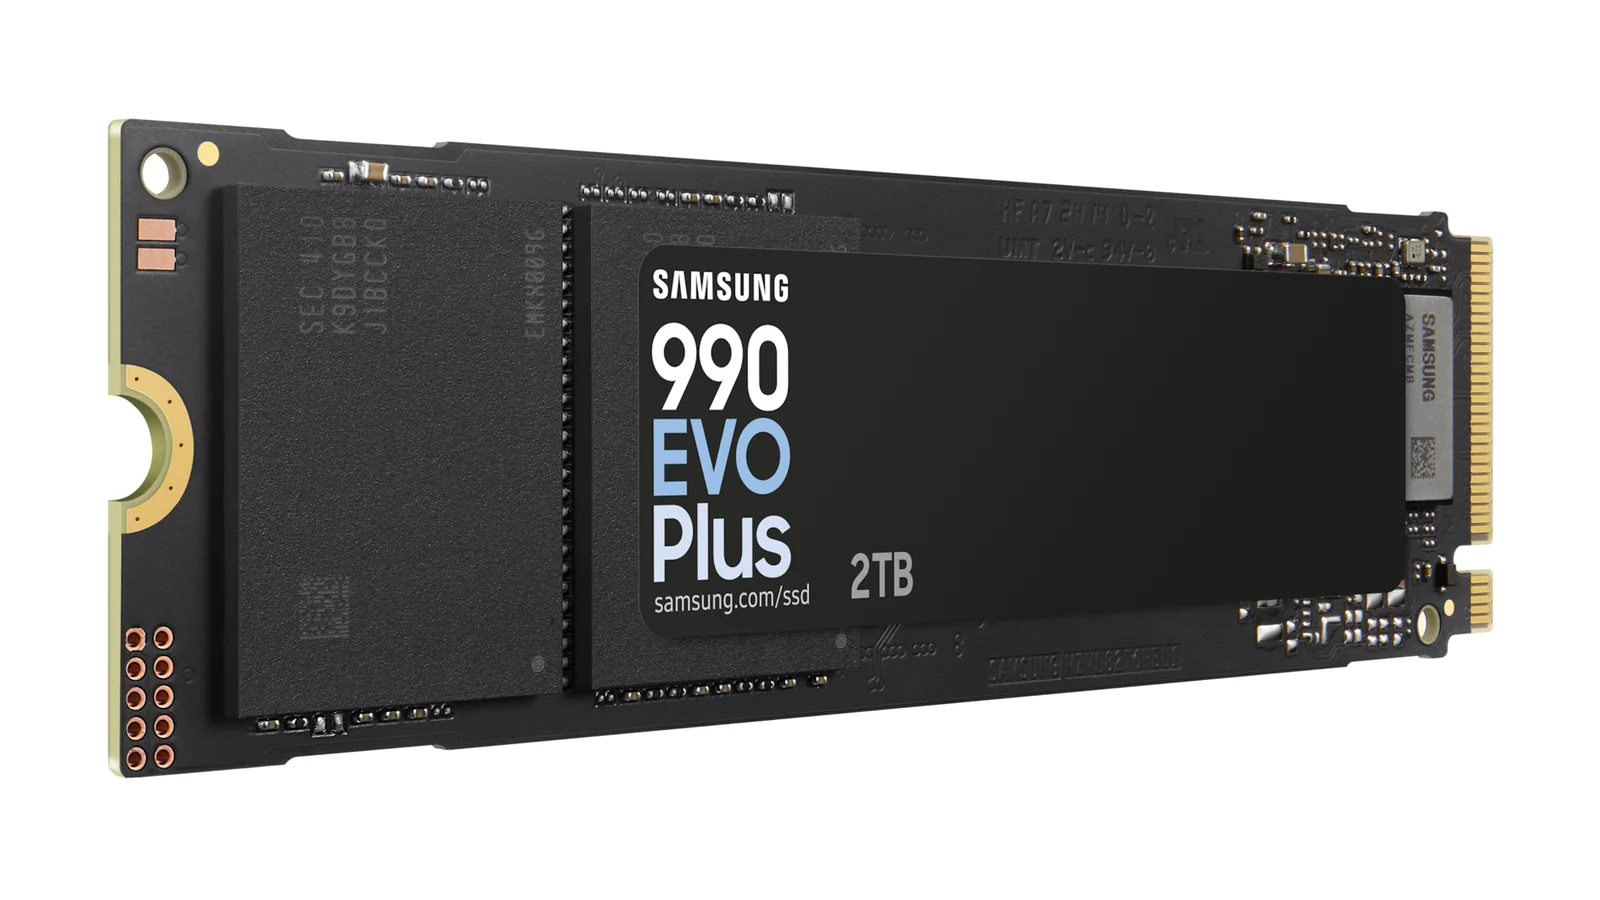
According to TrendForce, PC manufacturers have broadly reduced client SSD procurement during Q4 2026, limiting purchases to the quantities necessary to maintain production schedules. Some are also revising their Q1 2027 procurement plans downward as finished-device inventories remain elevated.
Manufacturers are resisting additional SSD price increases because higher overall component costs have already pushed up retail prices and weakened demand.
On the supply side, AI-related applications continue to compete for NAND flash production capacity. SSD suppliers are responding partly by imposing larger price increases on lower-capacity products, which generally offer less attractive production economics.
Competition is helping moderate increases in mainstream SSD capacity segments. TrendForce says Chinese suppliers and memory module manufacturers are securing additional orders by offering smaller price increases than some competing suppliers.
As a result, the firm expects client SSD contract prices to rise by less than 5% quarter-over-quarter in Q4 2026, a notable slowdown compared with the previous quarter.
For PC buyers, the distinction between contract prices and retail prices remains important. TrendForce’s forecasts concern prices negotiated between component suppliers and manufacturers, not the prices consumers pay for individual RAM kits, SSDs or completed gaming PCs.
The report nevertheless indicates that manufacturers are facing difficult choices between absorbing higher costs, increasing retail prices and reducing hardware specifications.
These pressures are consistent with concerns about declining PC shipments in 2027, as component inflation threatens to make new systems less attractive to consumers.
TrendForce’s latest research suggests that the immediate challenge is no longer simply securing enough memory and storage components. Manufacturers must also manage growing inventories and decide how much hardware consumers will be willing to pay for in 2027.
